BLOG
Roofing & Exteriors Resources in Magnolia, TX
Check Out Our Informative Blog!
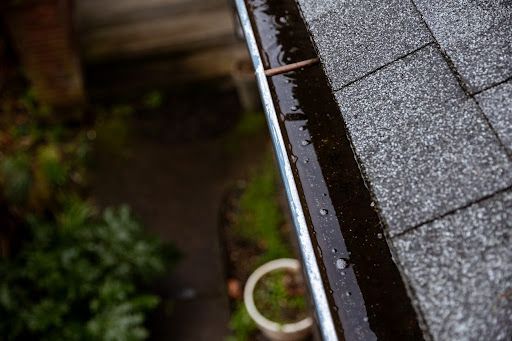
Prepare your roof for Texas summer storms with Exteriors of Texas LLC. Serving Magnolia, The Woodlands, Cypress, Houston, and beyond. Schedule your inspection today.
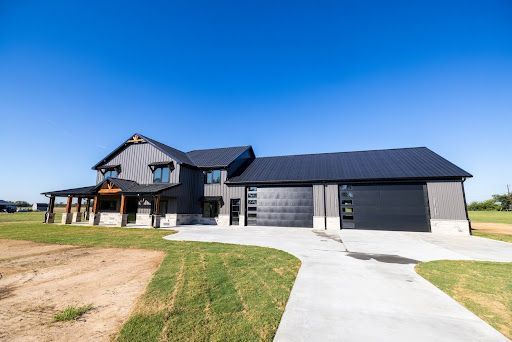
Discover barndominium roofing finishes and trends from Exteriors of Texas LLC, serving Magnolia, The Woodlands, and Houston, TX. Get expert advice on style and durability.
It does not take long living in Northwest Houston to understand that Texas weather is not something you negotiate with. One week in May you are cutting grass in bright sunshine, and the next a line of severe thunderstorms rolls through Tomball and Magnolia dropping baseball-sized hail and 70-mile-per-hour wind gusts. When that happens, your roof takes the full force of it. The first question most homeowners ask while standing in their living room staring at a water stain on the ceiling is not about how to fix it. It is about whether their insurance will actually pay for it. That is a reasonable question, and the answer is more complicated than a simple yes or no. Texas homeowners insurance policies have specific rules, exclusions, and deductible structures that directly affect how much you get paid and how fast. Knowing these details before you file a claim puts you in a significantly stronger position. What a Standard Texas Homeowners Policy Actually Covers Most standard homeowners policies in Texas are written on an HO-3 form, which covers your dwelling against all perils except those specifically excluded. Storm-related roof damage generally falls within covered perils, but the specific type of damage matters. Hail Damage Hail is one of the most common roofing claims in Texas, particularly in the corridor from Houston through Montgomery County. Covered hail damage includes bruised, cracked, or fractured shingles where the granule layer has been compromised. When granules are knocked off shingles by hail impact, the underlying asphalt is exposed and the roof's ability to shed water and handle UV deterioration is reduced immediately. Insurance adjusters look for impact marks, granule loss concentrated in one area, and denting on metal flashing, gutters, and HVAC units as evidence of a hail event. Wind Damage High wind damage, including shingles that are lifted, creased, or blown off entirely, is typically covered. The standard here is that the wind event caused direct structural damage to the roof system. Shingles that were already loose from age and simply finished separating during a moderate wind event are harder to claim successfully. Fallen Trees and Impact Damage If a tree or large branch falls onto your roof during a storm and causes structural damage to the deck, framing, or living space below, that repair is generally covered under a standard policy. The tree removal itself may also be partially covered depending on your policy's specific terms. What Insurance Does Not Cover Normal wear and tear, aging shingles losing granules from years of sun exposure, and maintenance neglect are specifically excluded under every standard Texas policy. If your roof is old and the shingles are deteriorating from age, a storm may accelerate that deterioration, but an adjuster will argue, often successfully, that the underlying condition was pre-existing. This is one reason why annual roof inspections matter. Documented proof of a roof's condition before a storm event gives you a strong baseline to work from. Policy Details That Directly Affect Your Payout Two homeowners on the same street with the same storm damage can receive very different insurance payouts depending on how their policies are structured. These are the details worth knowing before you need them. Replacement Cost Value vs Actual Cash Value This is the most important distinction in any roofing claim. A replacement cost value (RCV) policy pays what it actually costs to replace your roof today at current labor and material prices. An actual cash value (ACV) policy deducts depreciation based on the age of your shingles before writing the check. On an older roof, that depreciation deduction can be substantial, sometimes leaving you with significantly less than the actual replacement cost. Check your declarations page right now to confirm which type of policy you carry. Cosmetic Damage Exclusions Many Texas policies include cosmetic damage exclusions, particularly for metal roofing. If hail leaves dents in your metal panels but the roof is not actively leaking, some policies will pay nothing because the damage is classified as cosmetic rather than functional. If you have a metal roof or are planning to install one, read your policy carefully for this exclusion. It is worth paying a higher premium to remove it. The Texas Deductible Law Texas law is explicit on this: a roofing contractor cannot absorb, waive, or credit your insurance deductible. If a contractor offers to work with your insurance in a way that involves covering your deductible, that is insurance fraud under Texas law and can result in your entire claim being voided. You are required to pay your full deductible, and your insurance company will ask for proof of that payment before releasing final funds. Any contractor making that offer should be avoided. What to Do Immediately After a Storm The steps you take in the first 24 to 48 hours after a storm directly affect how strong your claim is. Do not wait. Document Everything Before Anything Is Touched Walk your property and photograph everything: the roof from ground level, any visible damage to gutters, fascia, siding, window screens, HVAC units, and fencing. Hail dents on an air conditioning unit are some of the clearest evidence of a hail event, and adjusters know this. Take photos of any shingles or roofing material on the ground. Note the date and time on your photos. If you can do this safely without going on the roof yourself, do it immediately. Stop Active Leaks with Temporary Repairs Your policy requires you to mitigate further damage. If you have an active leak, cover the damaged area with a tarp or have a contractor apply emergency roof covering. Keep the receipts, because most Texas policies reimburse reasonable emergency repair costs. Ignoring an active leak and allowing interior water damage to develop can give the insurance company grounds to reduce the claim. Get a Professional Inspection Before You Call the Insurance Company This is the step most homeowners skip and later regret. Before you call your insurer to open a claim, have a qualified local roofing contractor inspect the damage and produce a written assessment with photos. When you have that documented report in hand, you know exactly what you are claiming before the insurance company's adjuster ever sets foot on your property. It gives you a baseline that is difficult to dispute. Exteriors of Texas provides storm damage inspections across Magnolia, Conroe, Tomball, Montgomery, and the surrounding area. Our inspection report documents every item of damage with photos, measurements, and repair cost estimates. [Internal link: Contact us for a storm damage inspection] What to Expect When the Adjuster Arrives Once you file a claim, your insurance company will assign an adjuster to inspect the damage. Here is what most homeowners do not realize: the adjuster works for the insurance company, not for you. Their job is to assess the claim accurately according to your policy, but they are also working within a system that has financial incentives to minimize payouts. Having your roofing contractor present during the adjuster's inspection is one of the most effective things you can do. A contractor who knows how to identify storm damage, including damage that is easy to miss or dismiss, can point out items the adjuster might overlook and provide immediate documentation if something is not noted on the adjuster's report. This is not confrontational. It is a normal and accepted part of the claims process in Texas. After the adjuster visit, you will receive a scope of loss, which is a document listing what the insurance company agrees to cover and at what cost. Review this carefully against your contractor's estimate. Gaps between the two are common and are not always the final word. What to Do If Your Claim Is Denied or Underpaid A denied or underpaid claim is not necessarily the end of the process. Texas homeowners have rights, and there are several legitimate paths to challenge an outcome you believe is wrong. The first step is a supplement request. Your roofing contractor can submit a formal supplement to the insurance company with additional documentation, including photographs, measurements, and manufacturer repair specifications, supporting items that were missed or undervalued in the original scope. Supplements are common in roofing claims and most insurance companies have a process for reviewing them. If a supplement does not resolve the dispute, Texas law provides a right to invoke appraisal, where both sides hire independent appraisers and an umpire decides the final value. This process can be effective when the disagreement is about dollar amounts rather than coverage denial. If your claim was denied on coverage grounds rather than dollar amount, consult with a licensed Texas public adjuster or an attorney who handles insurance disputes before accepting the denial as final.
Learn how much a barndominium costs to build in Texas in 2026, including land prep, foundations, finishes, permits, and smart ways to manage your budget.
Explore how reflective cool roof materials from Exteriors of Texas LLC help Magnolia, TX area properties reduce heat and save on air conditioning costs. Call us today.
Learn what to expect during a commercial roof installation with Exteriors of Texas LLC in Magnolia, The Woodlands, CYPRESS, and Houston, TX. Discover our timeline, safety, and disruption strategies.
Discover why attic ventilation is crucial for roof longevity and energy savings. Exteriors of Texas LLC serves Magnolia, TX and surrounding areas. Learn more and schedule today.
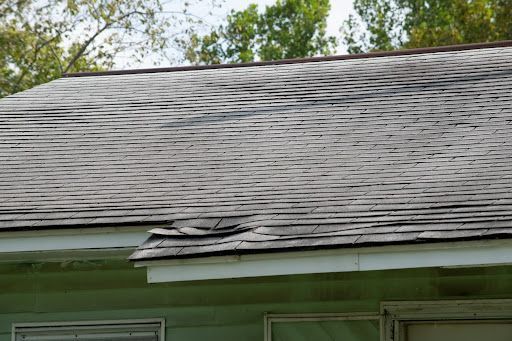
Discover why postponing roof repairs in Magnolia, Cypress, and Houston, TX can increase costs. Exteriors of Texas LLC explains timely service benefits for your home.
See how Exteriors of Texas LLC delivers roof transformations in Magnolia, TX. Local case studies highlight real project solutions for homes and businesses.
Storm damage your Texas roof? Follow this step-by-step guide to inspect, document, and restore your home fast with Exteriors of Texas.